
BORSA. — To preserve the corporal with decency and reverence when it was reduced to its present dimensions, the borsa (purse) was introduced. In ancient times the corporal was kept in special boxes or cases, or it was carried to the altar inside the Liber Sacramentorum. Today the borsa consists of two cardboard panels joined together and open on one side. It must be covered, at least on one side, with fabric of the same color and material as the sacred vestments. The interior may be made of silk or linen. It is not necessary for it to have a cross on it, but it may be adorned in various ways. Its use is not very ancient; Gavanto traces it back to the Council of Reims (11th century). Today it is obligatory according to the prescriptions of the rubrics of the Missal. The practice of distributing communion outside of Mass has also led to the obligation for the priest to carry the corporal to the altar himself in the borsa: this is the same one used for Mass and must be the color of the stole. For carrying communion to the sick, another borsa of white silk is also used, with a round and sturdy bottom to support the pyx or the small ciborium containing the particles, closed at the top by a cord to be worn around the neck. It
The facade must not be used to carry the Holy Oil, for which a violet one is employed. Finally, it should be recalled that the Sacred Congregation of Rites prohibited the use of bursae intended for corporals to collect alms.
Enrico Dante
---
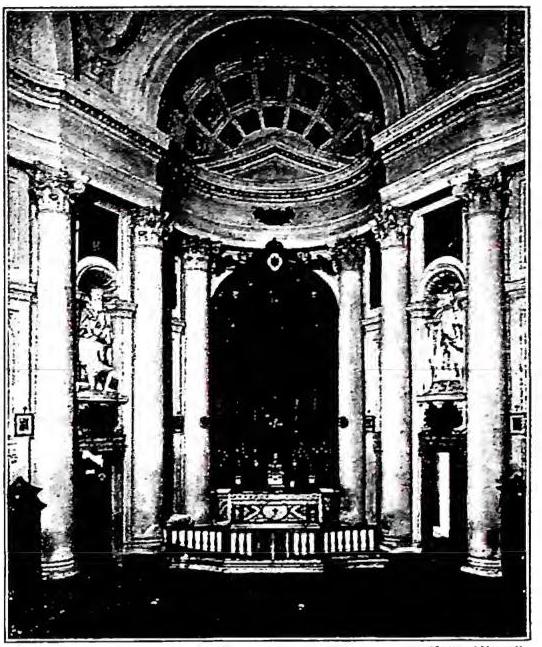
BORROMINI, FRANCESCO - Facade of the Oratory of the Filippini at the Chiesa Nuova - Rome.
BORSA. - I. The place where securities or goods are bought and sold; hence two kinds of b.: b. dei valori (stock exchange), where credit securities are traded (government bonds; shares and bonds of industrial, mining, commercial companies, etc.; coins and foreign exchange); b. merci (commodity exchange), where the most important goods are traded (raw materials, wheat, rice, sugar, coffee, etc.).
II. The operations of b. can be:
a) contratto a contanti (spot contract) or a termine con consegna (forward contract with delivery): the two parties actually exchange securities or goods and the price either at the time of the transaction or at the agreed term;
b) contratto a termine differenziale (differential forward contract): the securities or goods are not delivered and at mid-month or month-end only the difference in the price of the security or commodity during the period is paid; that is: if at the time of concluding the contract the price of the security was 100 while at the time of its expiry it becomes 101, the party who bet on the rise (bull) receives the price difference of 1 per security from the party who speculated on the fall (bear); the opposite would occur if at expiry the price had fallen to 99;
c) contratto a premio (option contract): the parties set a maximum limit on the difference up or down; payment will be made up to that limit when the price fluctuation of the security or commodity had exceeded it;
d) contratto a riporto (carry-over contract): one party (riportato) transfers to the other (riportatore) a certain quantity of securities with the express reservation, after a certain time, of being able to repurchase them: the same or an equal number of the same kind;
e) contratto a deposito (deposit contract): the reverse operation of that described in the previous paragraph.
In every b. a listino (quotation list) is displayed where the prices of securities or goods are recorded: the opening and closing prices; the highest and lowest prices. In the major b. of a country the entire economic life of that country is reflected and, by extension, the economic pulse of other countries also arrives there; hence they constitute centres of exchange, information and guidance of paramount importance.
III. MORALITY
Catholic moral doctrine is certain on this general principle: stock-exchange operations, considered in the essential elements that constitute them, are licit. For they result from the combination of originally licit contracts: e.g., a forward contract with deferred settlement reduces to a wager or an aleatory game, albeit under the guise of a sale; a report combines, in reverse order, a spot sale with another forward, and in cornering the whole set of stock-exchange operations aimed at concentrating in the hands of one or a few operators almost all the securities of a given kind is resolved. Indeed, some authors, against the misgivings of others, with licitness they also proclaim the utility of stock-exchange operations for the national economy: “it is in the public interest that there be some who, lured by the hope of gain, devote themselves to investigating these phenomena: thus prices are established more easily and securely, and industry and commerce are better promoted” (A. Tanqueray, Synopsis theologiae moralis, III, Rome 1929, p. 465). Therefore, stock-exchange operations, licit in themselves, can become illicit and unjust only by virtue of particular circumstances that insert themselves among the essential elements of the operations themselves, corrupting their moral goodness. The principal such circumstances are the following.The use of means already unjust or illicit in themselves, in order to provoke prices favourable to one’s own gain, with or without harm to others: e.g., spreading secret or false news about the prosperous or bankrupt state of a person or institution. Even operating on an excessive quantity of securities can give rise to various forms of illicit or unjust conduct. By provoking artificial prices beyond the maximum and minimum limits of the just and real price, private individuals can be harmed, which is contrary to commutative justice; or, without harming private individuals, the general economy of the nation can be disturbed, which is contrary to social justice: hence the moral obligation to observe the civil laws existing in the matter (A. Vermeersch, Theologiae moralis principia, responsa, consilia, II, 3rd ed., Rome 1937, p. 474). Moreover, excessive stock-exchange trading, even without altering the just price, can be unjust toward the counterparty if it exposes the operator to the risk of insolvency by undertaking risks beyond available capital; or it can expose a flourishing individual or family economic situation to the danger of considerable hardship: then, even without violating justice, imprudence is committed and a violation of moral duties toward one’s family or oneself is also incurred.
Monopolistic operations in securities are licit or illicit according to the ends to which they are directed. They are licit and useful if aimed at licit and useful ends, such as the defence of a security threatened by crisis or by ill-intentioned or merely imprudent operators; they become illicit and unjust if aimed at illicit and unjust ends, such as the ruin of a private person or institution, or the boycott of their licit speculations. Finally, it should be noted that, according to the decree of the Holy Office of 15 April 1885, ecclesiastics are obliged “to abstain from every contract that resembles the so-called gambling transactions of the stock exchange.”
Both because of the consequences that follow and because of the conditions presupposed, the difference between merely moral violations and violations that are also unjust must be noted. Injustice, in addition to moral wrongdoing, also generates the obligation to make restitution for the harm caused to others; this is not the case with merely moral violations. Yet for there to be an obligation of restitution, the circumstance that renders the operation unjust must meet three conditions: it must be truly unjust, i.e., injurious to another’s right; it must be effectively unjust, i.e., the cause rather than merely the occasion of that injury to a right; and it must be subjectively unjust, presupposing in the operator the awareness of such injury as produced by his action. If any of these conditions is lacking, the obligation of restitution lapses, even though the gravity of the moral violation may persist.
In the stock exchange, brokers, in addition to operators, can incur moral faults or injustices. Being specialized intermediaries, their faults, apart from their greater gravity and ease of commission, reduce to the common faults of all intermediaries.